

Why bother planning retirement in your 30s?
“Do I need a financial planner in my 30s?”
It’s a common thought. Retirement feels like a distant problem, something to worry about after the kids are grown or the mortgage is paid.
I used to think the same when I was contemplating retirement planning in my 30s and 40s. In my 20s and 30s, I didn’t give retirement much thought. Why would I? I had a final salary pension and a stable job.
But that all changed when I was made redundant at 40. I didn’t seriously start planning for retirement until my early 50s. Looking back, I realise how valuable those early years could have been.
The truth is: retirement planning isn’t just for the over 50s. It’s for everyone. And the earlier you start, the more options you’ll have.
The Power of Compounding
How much will you need in retirement? That depends entirely on what you want your future to look like. But one thing’s certain: starting early gives you a massive head start.
Let’s take an example.
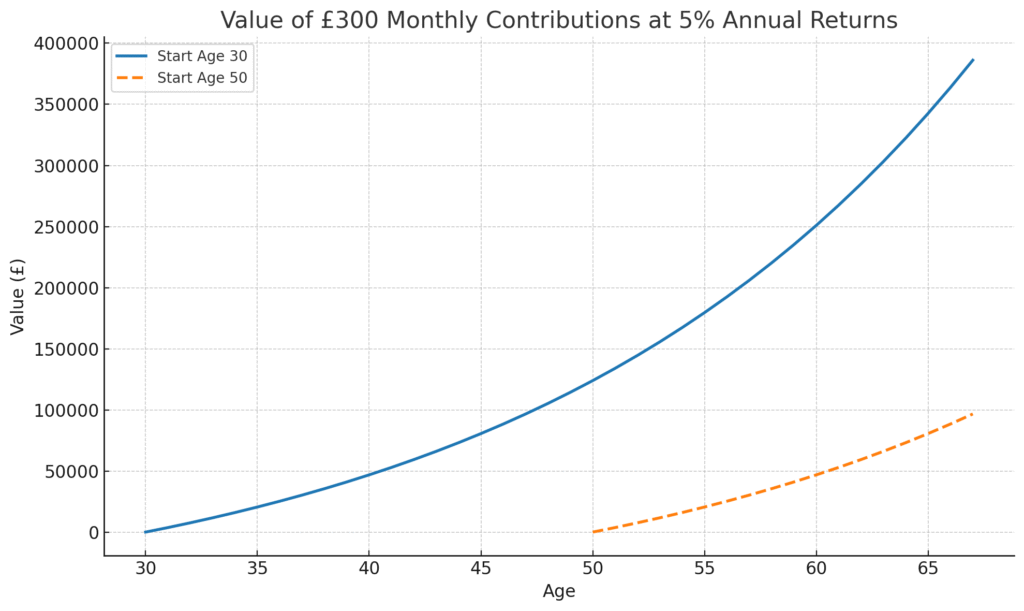
If you save £300 per month from age 30 to 67 at a 5% return, you could build a pot worth around £384,000.
If you wait until age 50 to start, you might end up with just £96,000.
That’s the power of compounding. The longer your money is invested, the more it grows. Effective retirement planning in your 30s can significantly impact these figures.
More Time = More Flexibility
Leaving it late often creates a sense of panic. We see this in investors chasing the latest trends, betting everything on crypto or stocks like Nvidia in the hope of making up for lost time.
Starting early removes that pressure.
It gives you the freedom to take manageable risks, make mistakes, and learn along the way. It also means you can take advantage of tax-efficient wrappers like pensions and ISAs, helping your money grow in a tax-free environment. Moreover, initiating retirement planning in your 30s offers you these benefits more efficiently.
At Manning Gee Investments, we encourage slow, steady growth. Building wealth gradually beats gambling on a lucky break.
It’s Not Just About Numbers – It’s About Lifestyle
Financial planning has changed. It’s no longer about selling products; it’s about helping people live the life they want.
We work with clients to identify what matters:
- Do you want to retire early?
- Take a career break?
- Support children through university?
- Move to part-time work in your 50s?
These life goals all shape the plan, and the earlier you start, the easier they are to achieve in retirement planning during your 30s.
Avoiding the Catch-Up Trap
I’ve been lucky. My pension gave me some breathing room. But many people face the prospect of needing to “catch up” later in life.
The problem?
When you’re 50 or 55 and realise you’re behind, it’s tempting to take bigger risks. That often leads to disappointment and stress.
Planning early allows you to avoid that trap. You don’t need a perfect plan from day one; what’s crucial is a foundation that evolves with you. This is why initiating a retirement strategy in your 30s is beneficial.
Key Questions to Ask in Your 30s and 40s
Your 30s and 40s are full of important milestones, career growth, starting a family, and buying a home. It can feel like retirement is last on the list.
But that’s exactly when these questions matter:
- What lifestyle do I want in retirement?
- Could I take a sabbatical or reduce hours in the future?
- Am I using my pension allowances effectively?
- Do I have a plan for big costs like university or paying off the mortgage?
Even just starting to think about these questions is a valuable first step towards retirement planning in your 30s.
Conclusion: A Roadmap That Evolves
Retirement planning in your 30s isn’t about having everything mapped out; it’s about starting the journey.
The earlier you begin, the more flexibility you’ll have later on. And with the right support, your plan can evolve as your life does.
At Manning Gee Investments, we help clients of all ages create retirement strategies that fit their goals, values, and lifestyle, not just their age.
Get in touch today to explore how we can support your financial journey—from your 30s to retirement and beyond.
General disclaimer: We sourced the data from external providers. While we strive for maximum accuracy, we cannot guarantee the reliability of the data they supply. The author writes the introduction from their perspective, reflecting their views, which may not align with those of Manning Gee Investments. Anyone considering a product or service based on this blog should seek professional advice or conduct their own research before deciding. The author bears no liability for decisions made based on this blog. Investments can rise and fall in value, and the return at the end of the investment period is not guaranteed—you may receive less than you originally invested.